How to Make a Car Insurance Claim: A Step-by-Step Guide
This blog is for marketing purposes only and does not constitute advice.
If you've just been involved in an accident or your car has been damaged, it can be hard to know what to do next. The claims process breaks down into 6 straightforward steps: check who your policy is with, contact their claims team, provide information about what happened, have the claim assessed, find out whether an excess applies, and follow the repair or settlement process. You don't need to have it all figured out before you make contact. Your insurer's claims team will guide you through what's needed. The exact process will depend on your circumstances, your Car Insurance Policy and your insurer.
How does the Car Insurance claims process work?
The details of every claim are different, but knowing the general process can help you understand what to expect before you ever need to make one.
With An Post Insurance, Car Insurance Policies are provided by a panel of insurers. If you need to make a claim, you'll deal with the claims team of the insurer that underwrites your particular Car Insurance Policy.
You can find your insurer’s details on your insurance disc and in your policy documentation.
From there, the claims process generally involves reporting what happened, providing the information requested, having the claim assessed and following your insurer's guidance on repairs or settlement where applicable.
Step 1: Check who your Car Insurance Policy is with
An Post Insurance is an insurance intermediary, so the first step when making a claim is to identify which insurer underwrites your Car Insurance Policy. You can check your insurance disc to find this information.
An Post Insurance currently provides Car Insurance through Aviva, AIG, FBD and Allianz. Each insurer has its own claims team, so you'll need to contact the appropriate one. Visit our Car Insurance Claims & Emergencies page for the current contact information for each insurer.
Step 2: Contact your insurer's claims team
Once you know which insurer underwrites your policy, contact its claims team to register your claim. You should do this as soon as possible after an accident. Have your Car Insurance Policy number and car registration available and your insurer’s claims team will then tell you what other information it needs and guide you through the next steps. You don't need to work out the entire claims process yourself before making contact. Your insurer's claims team can explain what is required for your particular situation.
Step 3: Provide information about what happened
When registering a claim, you'll need to provide information that allows your insurer to understand what happened. For an accident claim, you’ll need to include the date, location and circumstances of the accident, along with the other driver's details where applicable. Your insurer may ask for additional information or supporting evidence depending on the type of claim.
The information required for a theft claim, for example, won't necessarily be identical to what is needed for an accidental-damage claim. Follow the instructions from your insurer and provide the information requested as accurately as you can.
Step 4: Your insurer assesses the claim
Once the claim has been registered and the relevant information has been provided, your insurer can assess it. Exactly what happens at this stage depends on the nature of the claim. If your car has been damaged, your insurer may arrange for the vehicle to be assessed. Where the damage is covered under your Car Insurance Policy, the insurer can then organise repairs or a settlement, depending on the circumstances.
The level of cover you chose matters here. For example, Comprehensive Car Insurance covers accidental damage to your own car, subject to the terms and conditions of the policy, whereas Third Party, Fire and Theft Car Insurance, on the other hand, does not cover accidental damage to your own car where you are at fault. It does cover your car against fire and theft, as well as your liability for injury or damage caused to other people and their property, subject to the policy terms. This is why it's worth understanding the cover you've chosen before you ever need to make a claim.
Step 5: Find out whether an excess applies
An excess is the amount you may need to contribute towards an insured loss before the insurer pays the remaining covered amount. Whether an excess applies and how much depends on your Car Insurance Policy, underwriter and type of claim. Check your policy documentation for the excess that applies to your cover rather than assuming the same figure applies to every Car Insurance claim. Your insurer's claims team can also explain whether an excess applies to the claim you're making.
Step 6: Follow the repair or settlement process
If your claim is covered, your insurer will explain what happens next. For vehicle damage, this can involve arranging an assessment and repairs. Depending on the circumstances of the claim, a settlement may be made instead. It's important to follow the process set out by your insurer rather than assuming you should arrange everything independently. Claims can vary significantly in complexity, so there isn't one standard timeframe that applies to every case. Your insurer is best placed to update you on the progress of your individual claim.
Will making a Car Insurance claim affect my No Claims Discount?
It can, depending on the type of claim and whether you have No Claims Discount Protection. If you make a claim and don't have No Claims Discount Protection, your discount may be reduced or removed at renewal. However, not every type of claim affects it. With the insurers available through An Post Insurance, windscreen, fire and theft claims do not affect your No Claims Discount, even if you don't have No Claims Discount Protection.
No Claims Discount Protection is an Optional Cover available at an additional cost and subject to eligibility, though it isn't necessary in order to purchase a policy. Depending on the cover selected and your insurer, it can protect all or part of your discount if you make a claim. It's important to remember that protecting your No Claims Discount protects the discount and not necessarily the overall price of your future Car Insurance premium.
You can read more about how claims and protection work on our No Claims Bonus page.
Do I need to report a car accident to my insurer?
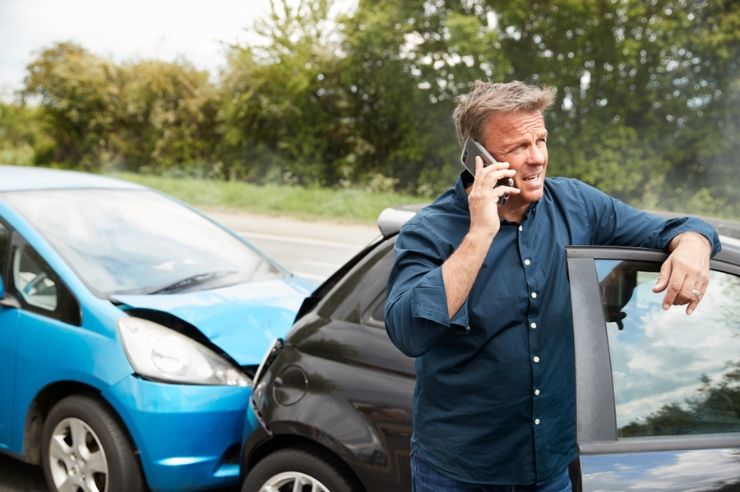
Generally, yes, even if you don't intend to make a claim. Most Car Insurance Policies require you to report any accident, regardless of fault or whether you plan to claim, since failing to disclose an incident could affect your cover if a related issue comes up later. Contact your insurer's claims team to let them know what happened; you can discuss with them whether a formal claim is the right next step for your situation.
Should I make a claim for every incident?
Whether to make a claim can depend on the circumstances, the type and extent of the loss or damage, your cover and the terms of your Car Insurance Policy. If an incident occurs and you're unsure how your cover applies, contact the relevant insurer for guidance. Don't assume that something is or isn't covered based solely on the apparent cost of the damage. Your insurer can explain how the policy applies to your particular circumstances and what information it requires.
How long does a Car Insurance claim take?
There isn't one fixed timeframe for a Car Insurance claim. Some claims are relatively straightforward, while others may require more information, assessment or involvement from other parties. The insurer underwriting your Car Insurance Policy manages the claim and is best placed to tell you what stage it has reached and whether anything further is needed from you. Be cautious about any general statement online that suggests every Car Insurance claim should be resolved within a particular number of days. The circumstances of individual claims can differ.
What if another driver was involved?
Where another driver is involved, the claims process can depend on the circumstances of the incident and questions such as who is considered responsible. When registering an accident claim, your insurer may ask for the other driver's details and information about what happened. From there, let the relevant insurer explain how the claim will be handled and what it needs from you.
If you need immediate guidance following an accident, use our Car Insurance Claims & Emergencies page rather than relying on a general guide like this one.
What information should I keep with my Car Insurance Policy?
It can be useful to know where to find your Car Insurance Policy number, policy documentation and details of the insurer underwriting your cover. Your insurance disc can also help you identify the relevant insurer if you need to contact a claims team and keeping your contact and policy information accessible means you won't have to search for it if you need help.
Because contact information can change, use the current Car Insurance Claims & Emergencies page when you need to contact a claims team. It’s a smart idea to save your insurer’s claims number in your phone contacts in case you need it, but regularly check the page to ensure the number you have saved is still up to date.
Understanding claims before choosing your Car Insurance
You don't have to wait until something goes wrong to understand how a Car Insurance claim works. When comparing cover, look beyond the premium and consider what the Car Insurance Policy actually covers, the excess that may apply and whether features such as No Claims Discount Protection are relevant to you.
An Post Insurance offers Car Insurance through a panel of insurers, with Comprehensive and Third Party, Fire and Theft options available.
When you're ready to explore your options, you can Get a Car Insurance Quote.
One Direct (Ireland) Limited, trading as An Post Insurance is regulated by the Central Bank of Ireland. One Direct (Ireland) Limited is a wholly owned subsidiary of An Post.
All the information on this blog is published in good faith and for general information purposes only. While An Post Insurance makes every effort to ensure that the information appearing on this blog is accurate and complete, it does not make any warranties about the completeness, reliability or accuracy of this information, whether express or implied, including but not limited to implied warranties of merchantability, fitness for a particular purpose or non-infringement. Any action you take upon the information you find on this blog is strictly at your own risk. An Post Insurance will not be liable for any direct, indirect or consequential losses and/or damages in connection with the use of, or action taken in reliance on information contained in our blog.